

Why Nigeria’s Banks Would Rather Lend to the Government Than to You
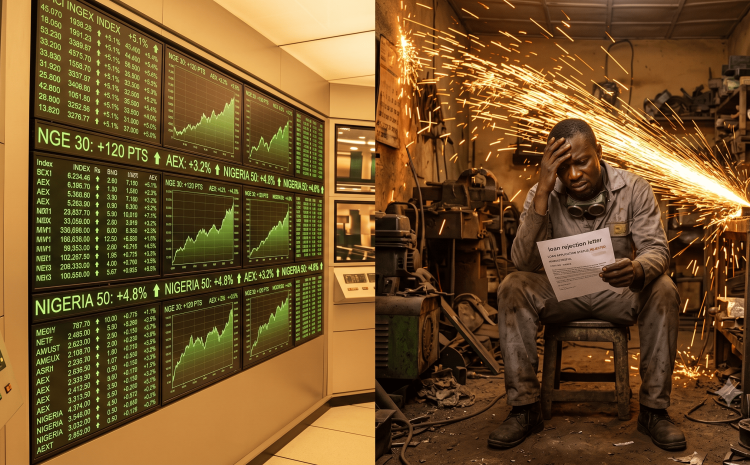
On Monday, Nigerian equity investors got N1.76 trillion richer in a single trading session.
That same morning, 96% of Nigerian businesses could not borrow a naira.
Both facts are true. Both are true in the same country, in the same week, out of the same pool of money.
The money never left. It found a better tenant.
Year to date, the Nigerian market is up 58.20%.
Inflation is cooperating too. Headline inflation has fallen to 15.91% in June 2026, down from a 34.80% peak in December 2024. That is the number the tightening was for, and the tightening worked.
Now hold that against the other ledger.
Credit to Nigeria’s private sector sits at roughly 13% of GDP. Kenya runs 32%. South Africa runs 70%. Of the country’s 40 million MSMEs, the businesses carrying 92.3% of Nigerian employment, only 4% can reach formal bank credit. The financing gap behind that number is estimated above $200 billion.
The market went up. The builder did not get in.
Is this greed or rationale?
Follow the arithmetic a Nigerian bank ran this year. The Monetary Policy Rate climbed from 18.75% in January 2024 to 27.50% by November of that year. At that rate a bank can lend to the Federal Government and collect 20% to 21%, guaranteed, no default risk, no collateral to chase, no site visit.
Or it can lend to a fabricator in Aba at 28% to 46% and hope.
A 2026 budget deficit near N20 trillion means the government keeps showing up to borrow, and keeps offering that risk free return. Every naira that goes there is a naira that does not reach a workshop.
Nobody in this story is behaving badly. The incentive is simply pointed away from the builder, and it has been pointed that way long enough to become the architecture.
This is what 51% looks like from the inside.
51% of Nigeria’s informal businesses have never taken a formal loan, and do not intend to.
Read that as a verdict, not a statistic. These are operators who watched the terms, priced their odds, and opted out of the banking system entirely.
We have written before about owning the rails under the informal majority, about the N5.19 trillion sitting outside Nigerian banks. This is the other half of that story. The financing was never refused. They were never offered on terms a trader could accept.
Somebody already proved the loan works.
Look south. Bridgement has distributed over $123 million in South African SME loans since 2016, underwriting on AI rather than on the land title a small business does not have. This year it raised $20.3 million, and the money came from Rand Merchant Bank and Standard Bank.
Read that last part again.
The incumbent banks did not build the product. They funded the company that did.
That is the shape of the opportunity, and it is not theoretical. The same institutions parking at 20% risk free will happily buy the loan book once somebody else has proved the underwriting.
The gate just opened.
On July 20, Nigeria’s Federal High Court upheld the Federal Competition and Consumer Protection Commission’s authority over digital lending, clearing the interim order that had frozen enforcement since April. The DEON Regulations are live again, carrying fines up to N100 million or 1% of annual turnover.
To a predatory loan app, that is a threat. To a serious lender, it is the thing that was missing: a perimeter, a standard, a reason for a pension fund to take your paper seriously.
Regulation is what turns a hustle into an asset class.
Who wins from this: the underwriter who can price a Nigerian small business without a land title. Movable collateral registries, receivables and inventory finance, alternative data models built on the transaction history that retail operating systems and payment rails are already generating. The data problem that made this lending impossible in 2016 has been quietly solved by everyone who spent the last decade digitizing the corner shop.
Who gets squeezed: the banks whose entire credit competence is collateral valuation, and who will discover that a 27.50% policy rate does not last forever.
The gap: 38.4 million Nigerian businesses with no lender, sitting next to a stock market that added N1.76 trillion in 1 session because the money had nowhere better to go.
Closing a gap that size takes 3 kinds of people in 1 room: the operator who knows what a working capital cycle actually looks like, the underwriter willing to price it, and the regulator drawing the perimeter around both. The Business Week Afrika Summit on October 1 and 2 exists to put them there.
Secure your seat and join the builders deciding where Africa’s capital finally lands: https://apps.little.africa/events/105
The capital came home to Nigeria this year, and it went looking for somewhere safe to sit.
40 million businesses are still waiting for someone to make the case that they were the safer bet. Will you be the one who underwrites them.